Contractor Prequalification Standards for Last-Mile Networks
Systematic vetting keeps last-mile networks compliant with labor law and ready to bid.
Last-mile delivery is the most expensive leg of fulfillment, and it has become the most operationally demanding to staff. A single route can run anywhere from a few dozen stops to well over a hundred, all packed into one shift window, and a network moving real volume might have hundreds of contractors on the road at the same time. If one credential check on one driver gets missed, that gap doesn't stay contained to one job. It rides along on every stop that contractor makes, until someone catches it, and in a manual system that might be never.
The USPS move announced in December 2025 makes the scale challenge of vetting contractors concrete. The Postal Service said it would open its more than 18,000 destination delivery units to bids from shippers of all sizes, with service under accepted agreements starting in the third quarter of 2026. It's a new front door into the largest delivery network in the country, a minor-sounding procurement update that actually requires any operator who wants through it to prove, on paper, that its contractor base is ready to work before the first package moves. A spreadsheet and a part-time compliance clerk cannot do that at 18,000 locations. The entry requirement itself is the argument for systematizing prequalification: the networks that can show their contractor readiness in a structured, repeatable way are the ones that get to bid, and the ones that can't are stuck watching from outside.
What misclassification exposure means for a last-mile operator
Prequalification is about keeping the entire contractor model legally intact, and that model now stands on shifting ground. The definition of "independent contractor" has moved at the federal level twice in less than a year. In May 2025, a federal labor agency told investigators to go back to the older "economic reality" test. In February 2026, the DOL formally proposed scrapping the 2024 rule altogether in favor of a framework built around two core factors: how much control the company exerts over the work, and how much opportunity the worker has for profit or loss.
A friendlier federal posture doesn't make the exposure disappear. California, Massachusetts, and New Jersey all run the ABC test or something close to it, and that standard applies regardless of what Washington decides. Most large last-mile networks run drivers across state lines, so an operator can be compliant under the new DOL framework in one state and dead wrong under state law in another, on the same day, with the same contract.
The PDX North case shows what happens when you test that gap. In March 2026, the last-mile automotive parts distribution company settled misclassification charges after the state found it had misclassified a large number of its delivery drivers as independent contractors. That settlement is now the reference point for how fast a contractor compliance gap turns into a legal and financial liability.
The exposure now appears earlier in a company's life too, at the point of sale. W-2 versus 1099 driver classification, with particular attention paid to California's AB5 and the current DOL rules, is now standard due diligence in last-mile acquisitions. Buyers now price this risk directly into what they'll pay for a last-mile business, so sloppy contractor classification doesn't just cost money if regulators catch it. It costs money the moment someone tries to sell the company.
The three insurance requirements that define the prequalification floor
Three types of coverage, taken together, set the minimum bar a contractor has to clear before taking a route: occupational accident, commercial auto, and cargo.
Occupational accident insurance exists because independent contractors are not employees, and in most states that means they don't qualify for workers' compensation. Without this coverage, a 1099 driver hurt on the job has no safety net, and the operator has no buffer against the claim that follows. No federal law or FMCSA rule mandates this coverage as a filing requirement. The pressure to carry it comes from state workers' comp law and from the contract terms that motor carriers, brokers, and shippers impose on the people they hire. Skipping it leaves not just a driver exposed, but the operator too. A single uncovered injury claim can become the evidence a regulator uses to argue the contractor was never really independent.
Commercial auto insurance comes with a federal floor: FMCSA sets minimum liability coverage for general freight carriers running interstate. That floor is the bare minimum, not the standard that actually governs most last-mile work. Amazon and Walmart, among other major retail and logistics partners, require specific coverage types and limits well above what FMCSA requires, as a condition of working with them. A contractor running on a personal auto policy can't meet any of this, because personal policies carve out commercial activity by name. That driver is, by definition, uninsurable for delivery work, no matter how clean the license or the background check.
Cargo coverage, often bundled with hired-and-non-owned auto coverage, closes the gap that remains for contractors who use their own vehicles. It covers what a personal auto policy won't touch once that vehicle is doing commercial delivery work. When a package gets damaged or a vehicle is involved in an at-fault incident mid-route, this layer gives the operator a documented claim path instead of an uninsured mess.
None of these three are internal policy preferences an operator can waive to move faster. They are externally enforced, by regulators in the case of FMCSA minimums and by contract in the case of Amazon, Walmart, and similar partners. Verifying certificates at onboarding is the floor, not the finish line. You should re-verify at least once a year, run quarterly checks on higher-risk contractors, and back this with a compliance tool that flags certificates before they lapse, not after.
Credentials, documents, and background checks that must clear before a contractor touches a route
Insurance clears one layer of risk. A full credential stack has to clear before a contractor can get assigned a route.
Start with the paperwork. A W-9 establishes the contractor's taxpayer identity and is required for 1099-NEC reporting at year-end, no exceptions. Business entity documentation, an EIN and Articles of Organization, signals that the contractor is running an actual independent business rather than functioning as an employee in all but name, which matters directly for classification defense given everything in the section above. A valid driver's license, matched to the correct vehicle class, has to be on file and current. A background check covering criminal and driving history is required as a condition of participation by most major shippers and retail programs. Drug screening is mandatory for DOT-regulated operations and is increasingly showing up as a contract condition from large retail partners even outside those regulated segments.
Where vehicle weight and route type bring DOT rules into play, the requirements get more specific. CDL verification and medical certification apply once GVWR and route type cross certain thresholds. DOT still enforces Driver Qualification File requirements for non-CDL drivers operating vehicles above a set weight threshold, so "no CDL required" doesn't mean "no file required." Safety performance history and hours-of-service documentation are now showing up as contract terms major shippers impose on top of the regulatory floor.
Vehicle readiness is its own line item. Inspection records need to confirm the vehicle actually meets the equipment standard for the routes it's being assigned to, and those standards differ between a box truck and a cargo van depending on the shipper and the route. Rocky Transport's 2025 breakdown of last-mile programs notes that technology, route optimization software, GPS tracking, handheld scanners, has become a standard program requirement across operators. If a contractor can't access that technology stack, it isn't ready to dispatch, no matter how clean the license and insurance look.
Some verticals stack additional requirements on top of all of this. Medical courier networks typically require HIPAA and OSHA bloodborne pathogen certifications at onboarding, though the specifics shift by network, client, and cargo type. The network generally isn't providing that training; it's asking the contractor to produce a certificate proving they already have it. White glove delivery, pharmaceutical transport, and refrigerated grocery each carry their own added credentials, so an operator moving into any of those segments has to map those requirements into the standard intake process before it deploys a single driver there.
Continuous Monitoring vs. the Static Onboarding Checklist
A checklist cleared once at onboarding tells an operator nothing about whether that contractor is still compliant a month later, platforms like GigSafe, a 1099 workforce operations platform for delivery companies that automates credential tracking, insurance verification, and compliance monitoring across contractor networks, exist precisely because that gap compounds quickly. Insurance certificates expire. Credentials lapse. A driver who passed every check at intake can be running uninsured or uncertified within weeks, and a one-time intake process has no way to catch that before the contractor gets handed another route.
The cost of missing that lapse isn't paperwork catching up later. If a non-compliant contractor is dispatched and something goes wrong on the route, the operator's classification defense, its insurance coverage, and its standing with the shipper are all exposed at the same moment. So one expired certificate can unravel three separate protections in a single incident.
CXT Software's approach to dispatch integration illustrates what the fix actually looks like in practice: compliance status tied directly to the dispatch system, so a contractor who falls out of good standing is automatically ineligible for new assignments the moment that happens, and automatically reinstated the moment the issue clears, without a human having to notice, flag, and manually re-approve the file. That auto-reinstatement piece matters as much as the block does. A compliance issue that takes days to clear in the back office is a contractor sitting idle and a route going uncovered, and that delay costs the operator capacity it didn't need to lose.
Quarterly insurance re-verification is the baseline cadence most operators should be running. You now need a compliance-tracking layer that flags expiring driver files in between those cycles; it's no longer just a nice feature. The underlying principle holds regardless of the specific tooling: compliance checks that happen at the moment of dispatch make non-compliance impossible to miss. Checks that happen on a quarterly audit schedule only make non-compliance something someone eventually notices, usually after it already mattered.
Automating the prequalification pipeline lets operators scale without adding headcount
Everything in this piece, the insurance floor, the credential stack, the continuous monitoring, only holds up at volume if automation runs the back-office work instead of headcount. A process built on manual review stops working abruptly when volume rises, usually right when the operator needs it most.
Onboarding is where this appears most clearly. Agentic dispatch and routing platforms in 2026 are built to handle routine exception handling and compliance checks as autonomous actions. That shift means operations scale with order volume instead of scaling with the size of the compliance team, which is the entire point. When a contractor clears credential submission and insurance verification faster, it moves into active status faster, so a network can cover more routes without hiring a single additional person to process paperwork.
Payment automation also functions as a retention tool. Where instant payment rails like RTP or FedNow are available, a payout can land in a contractor's account within minutes of being initiated. That kind of same-day pay infrastructure used to be something only the largest enterprise platforms could offer, and it isn't anymore. Pay speed and pay reliability are turning into recruiting and retention variables in their own right, and a network that automates fast, reliable pay is going to out-compete one still running manual weekly disbursements for the same pool of drivers.
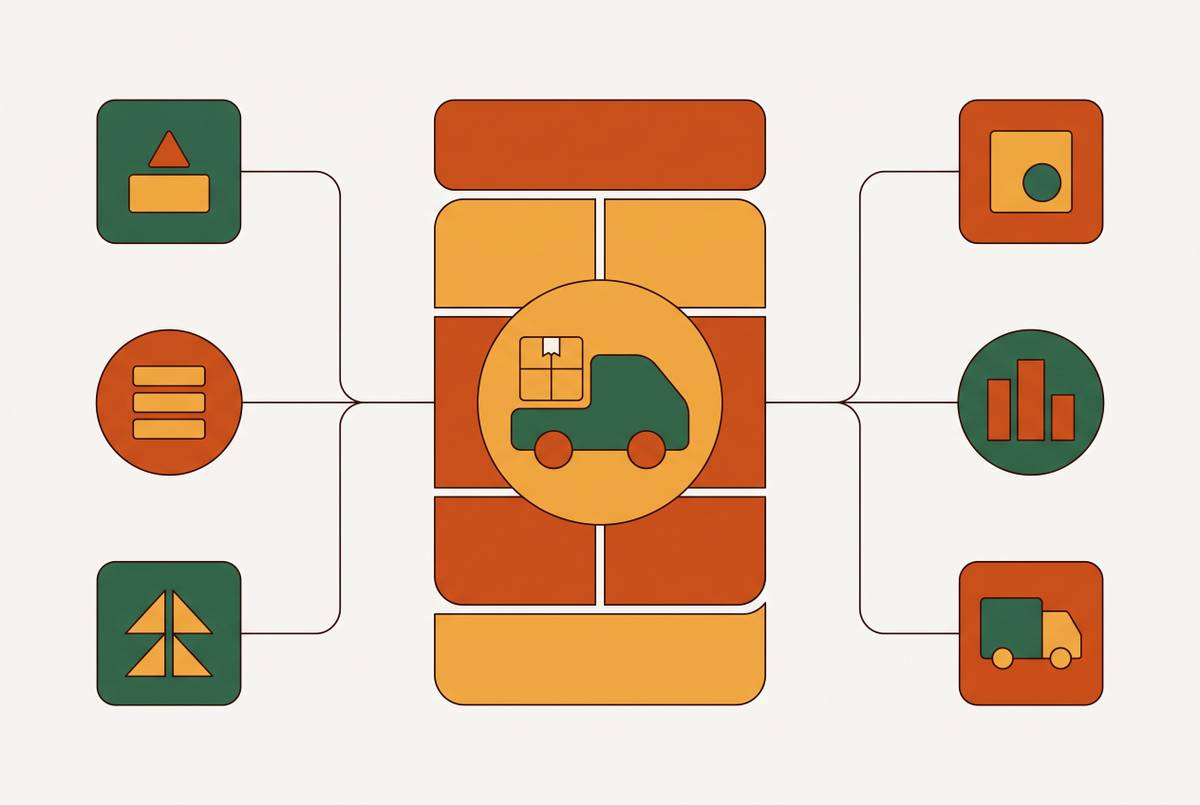
The operators who end up ahead run onboarding, real-time compliance monitoring, insurance tracking, and payment through one connected system, instead of four disconnected tools that each need someone to reconcile them by hand. A system that closes the loop from the moment a credential comes in, through dispatch eligibility, all the way to the contractor getting paid, without a human stitching the steps together by hand is the one that scales. A system that can't answer yes to that question isn't ready for the scale last-mile networks are now operating at, USPS DDU bids included.